What Happens If You Don't Pay Property Taxes in Connecticut
If you're reading this, there's probably a tax bill on the kitchen table you've been trying not to open. It's OK. You probably have more time than you think.
Most people assume the town can take the house the day after a missed payment. It can't. Connecticut's process is slow, it's written into state law and it gives you rights along the way. I've been working with Connecticut homeowners since 2011 and back taxes come up more than you'd guess. On a family property in Higganum, there were nine heirs spread across the country, a court backlog and back taxes. We paid the back taxes and stayed with it for the 42 months it took to close.
Nothing Happens Overnight
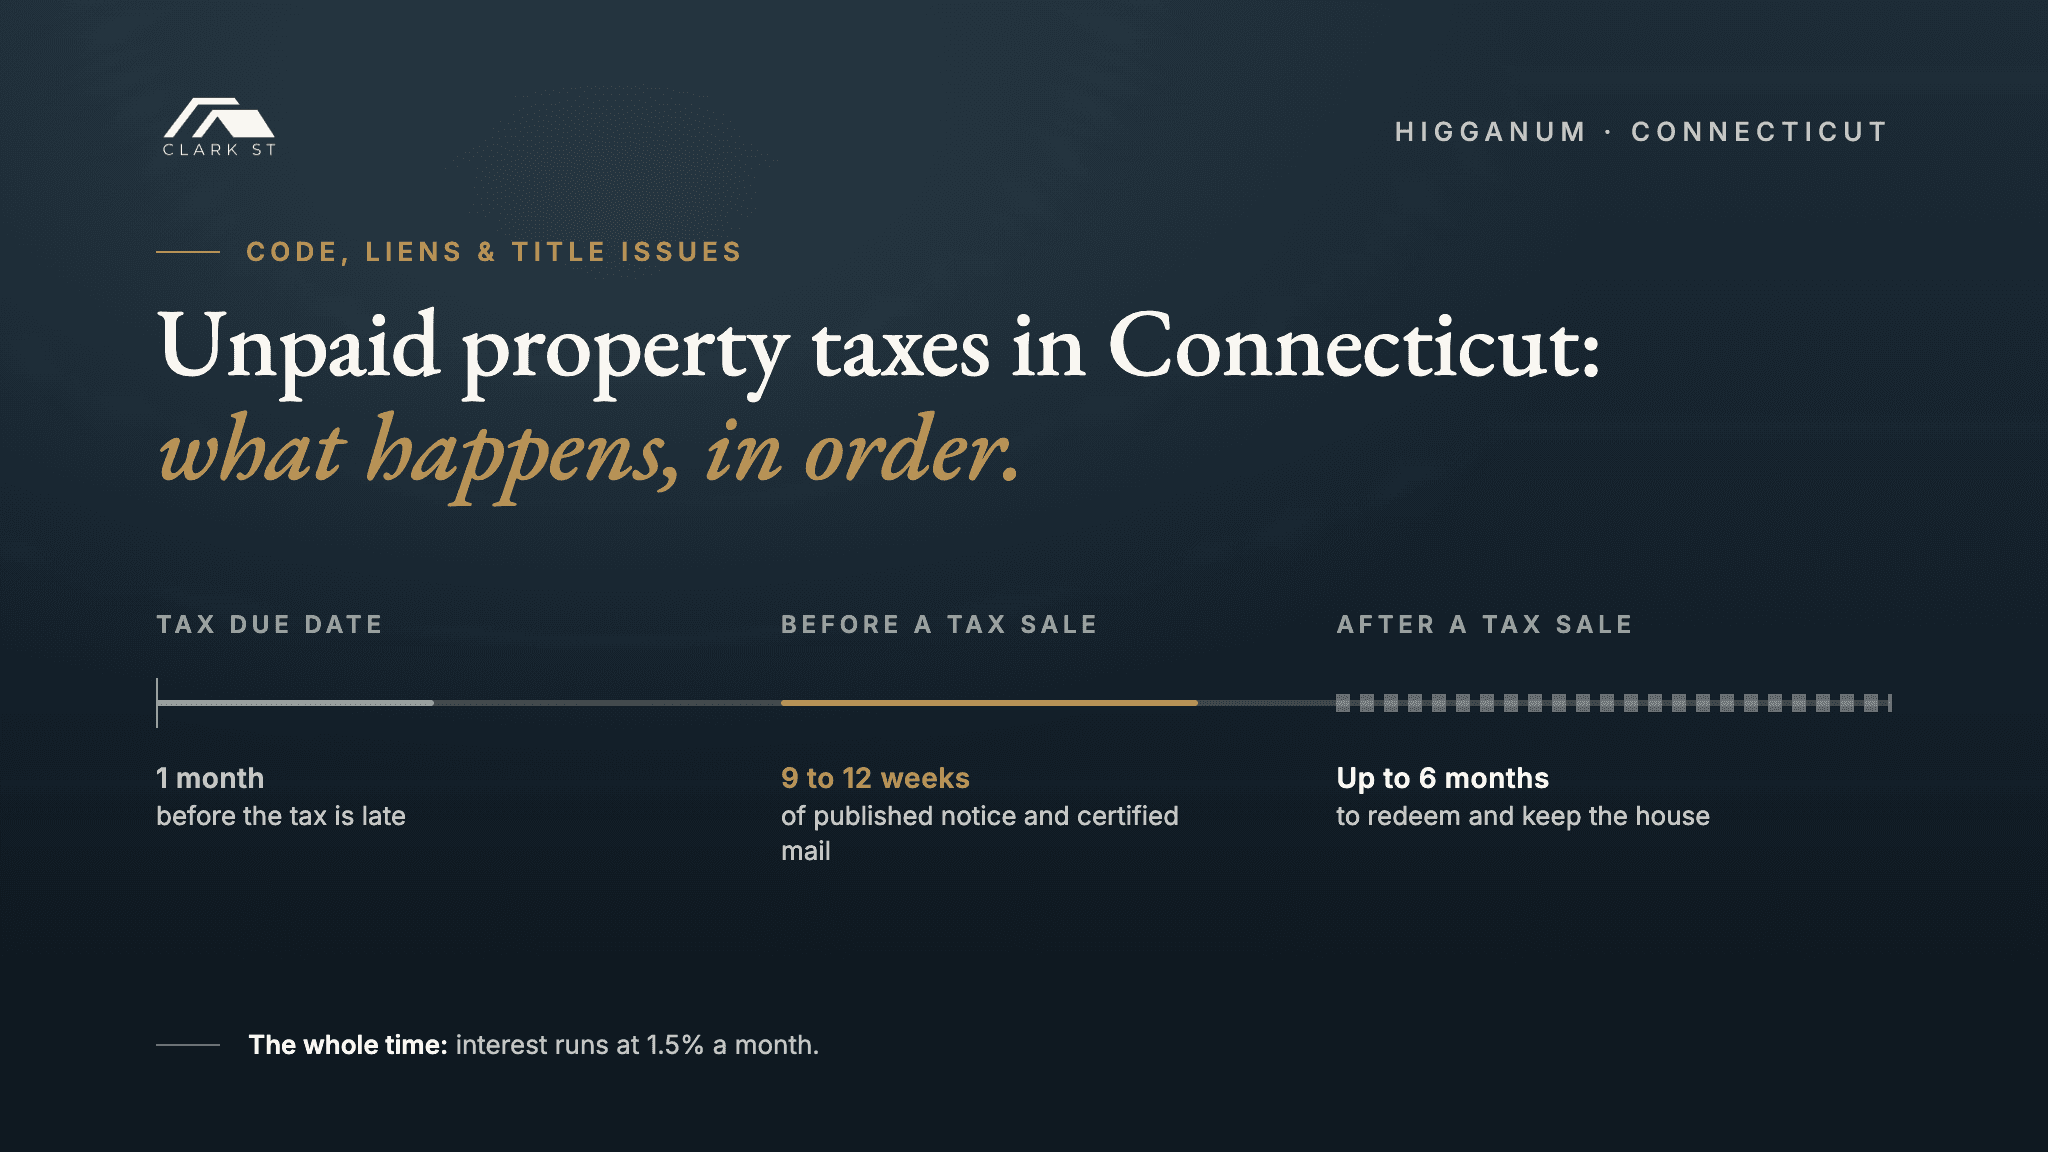
The grace period. Connecticut gives you 1 month after the due date before a tax is late (CGS 12-146).
The interest. After that, interest runs at 1.5% a month or 18% a year, counted back to the original due date (CGS 12-146). On a $3,000 installment, that's $45 a month.
The lien. The unpaid tax becomes a lien on the house. The tax collector can record it on the town land records after mailing you notice at least 15 days ahead (CGS 12-175). A lien doesn't mean you've lost anything. It means the debt stays with the property and gets paid off when the house sells or you refinance.
The paper trail. The law requires notices along the way. Before a tax sale, you get certified mail and the sale is published 9 to 12 weeks ahead (CGS 12-157).
What the Town Can Do Next
Once there's a lien, a Connecticut town has a few tools.
- Sell the lien. The town can sell or "assign" your lien to a private company (CGS 12-195h). The company has to send you a letter within 60 days saying who holds it. It gets the town's rights and can add attorney's fees and certain costs. The law also gives you protections. The company is treated as a consumer collection agency, it has to give you a payoff statement and for liens assigned on or after July 1, 2022, it can't start a foreclosure until a year after it bought the lien.
- Hold a tax sale. The town can auction the property after giving notice. You then get up to 6 months to redeem it and the house stays yours (CGS 12-157). To redeem, you pay the taxes, interest and charges owed at the time of the sale, plus 18% a year on what the buyer paid. The window can be as short as 60 days for abandoned properties. If the sale brings in more than what's owed, the town can't keep the extra. It's held in escrow and you may have to claim it, so talk with an attorney about how.
- Foreclose in court. The town or the lien holder can file a lawsuit. You'll be served legal papers and a judge sets the date by which you can pay and keep the house (CGS 12-181). You're allowed to show up, ask questions and ask for time.
What You Usually Can't Do
You can ask the town to forgive the interest, but in most cases it can't. State law sets the rules and the rate. The tax collector doesn't have a lot of leeway to waive it, if any.
- Ignoring it doesn't pause it. Interest keeps running.
- Partial payments help, but they don't touch the tax first. In Connecticut, payments go to fees and interest before the tax itself (CGS 12-144b).
- Your mortgage company will get involved. Most mortgages require you to keep the taxes paid. Lenders often pay the back taxes themselves, add them to what you owe and set up an escrow account, which raises your monthly payment.
Start With Free Help
Before you think about the house at all, make these calls.
- Your tax collector. Ask exactly what you owe, what interest is running and whether your lien has been sold. Most collectors will talk with you about a payment arrangement.
- Your assessor. If you're 65 or older or disabled and your income qualifies, the state Circuit Breaker program can cut your tax by up to $1,250 a year for a married couple and $1,000 for a single homeowner. Many towns add their own freezes, deferrals and exemptions for seniors and veterans. There's an application window each year, so ask when it opens.
- CHFA's Emergency Mortgage Assistance Program (EMAP). If you've fallen behind on property taxes you pay yourself, not through escrow, because of a hardship beyond your control, EMAP may be able to bring you current. It's a loan, not a grant. It comes due when you sell, take out new financing or move out. Call (860) 571-3500.
- Foreclosure mediation. If your mortgage company files a foreclosure, Connecticut's mediation program is open to you. You need to ask for assistance from this program within 15 days of the return date on the summons. Mediation alone doesn't stop the foreclosure.
- Free advisors. A HUD-approved housing counselor, Statewide Legal Services of Connecticut and 2-1-1 can all help at no cost. A bankruptcy attorney can tell you whether a Chapter 13 plan would let you repay back taxes over time.
If Keeping the House Isn't Your Goal
Some people make those calls and decide the house doesn't fit their life anymore. That's a reasonable answer too.
- If you want the most money: list with a trusted, local agent. Someone who knows your neighborhood and has buyers ready to buy. The back taxes get paid out of the sale at closing. If you're not sure who to call, set up a call with me. I work with realtors all over Connecticut. I'm happy to refer you to a trustworthy realtor to take good care of you and your family. I never request or accept a referral fee from those realtors. I do business with them because I know they serve their clients with integrity.
- If you want speed and certainty: Clark St Homes can be a good option, especially when the house needs work. If we're the right fit, you get a written cash offer within 24 hours of our visit, based on the house's condition. We close in 2 to 4 weeks with no repairs, no cleaning, no showings and no commissions. But keep in mind, if top dollar matters most, the realtor route will usually get you more.
How to Read Your Own Situation
- Taxes are late, but no letters about a sale or a lawsuit. You're in the least expensive part of the process. Call the tax collector to talk about your options.
- A letter says your lien was assigned. Call the company named in the letter and ask for a written payoff with every fee listed.
- You've received a tax sale notice or court papers. You still have rights and a deadline. Talk with legal aid or an attorney about how they apply to you.
- The house is paid off, you're on a fixed income and the taxes outgrew your ability to keep up. Start with your assessor.
For every option in more detail, read Behind on Property Taxes in Connecticut: Your Options. If you're behind on the mortgage too, start with our Connecticut Foreclosure Guide.
If you'd like to talk any of this through, I'm happy to get on a 20-minute Zoom call and answer your questions. You don't have to be thinking about selling.
Please remember, back taxes are a problem but you have a lot of options. Most of them start with one phone call to your town hall.
This article explains how Connecticut property tax collection works in general. It isn't tax or legal advice. Rules and practices vary by town and laws change. Talk to your town tax collector, a CPA or an attorney about your situation.
About Ed Mathews and Clark St Homes
Ed is the founder of Clark St Homes, based in Higganum, Connecticut. He has been helping homeowners since 2011. He and his team help people work through difficult situations: foreclosure, probate, inherited property, divorce, tired landlords and houses that needed more work than a conventional sale could handle. Clark St Homes is a professional home buyer. Clark St serves homeowners, landlords and executors across Hartford County and Middlesex County, as well as Guilford and Madison.
Situations we help with
- Behind on payments or facing foreclosureHow foreclosure works in Connecticut and what you can still do about it.
- Behind on property taxesWhat the town can do, your rights and who to call first.
- Inherited a house or handling probateSelling an inherited Connecticut house without fixing it up first.
- Done being a landlordSelling a Connecticut rental, occupied or vacant.
Before you decide
- Why a cash offer comes in below ZillowWhere the difference goes, from repairs to commission, and when listing is the better call.
- How long closing takesA cash sale skips the bank, but title still takes time. Why most closings take 2 to 4 weeks.
- Leaving the house as it isTake what matters to you and leave the rest. No dumpsters, no estate sale.
- Free guide: Facing Foreclosure in Connecticut14 pages: what actually happens, the one deadline most homeowners miss and every real option you still have.
Get Your Cash Offer
No fees. No commissions. No repairs.